IRS Tax Debt Attorney: A Guide to Solving Your Tax Problem
Facing the IRS? An IRS tax debt attorney can help. Learn what they do, when you need one, and how to resolve your tax debt for good. Get a free analysis.
In this article
- That IRS Notice Arrived What Now
- What to do in the first few days
- Why calm action beats panic
- What an IRS Tax Debt Attorney Actually Does
- Representation starts with control of communication
- The debt has to be broken apart before it can be solved
- Why this is different from standard tax prep
- When You Absolutely Need an Attorney
- Red-flag situations
- Why other professionals bring in tax debt counsel
- When waiting makes things harder
- The Tax Resolution Process Explained
- Step one is analysis before commitment
- Form 2848 changes who is steering the case
- What the middle of the case looks like
- What clients usually feel once the process starts
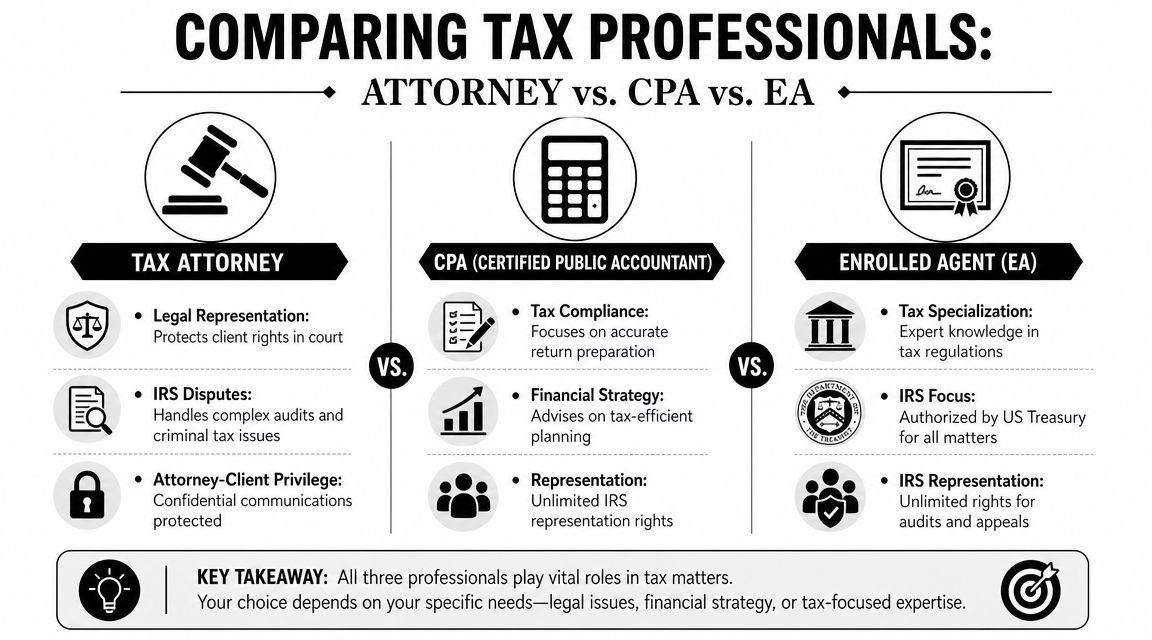
- Attorney vs CPA vs EA Who Should You Call
- Tax Professional Comparison Attorney vs CPA vs EA
- The practical way to decide
- Choosing the Right Attorney and Understanding Fees
- What to ask before you sign
- Why free analysis first can make sense
- Fees should match the work
- Common Outcomes and Your Next Steps
- Common resolution paths
The envelope is still on the counter. You've read the first line three times, your stomach dropped once, and now you're trying to figure out whether this is a paperwork problem, a payment problem, or the start of something much bigger.
That reaction is normal. IRS notices are written in a way that makes people feel cornered. The better response is slower and more practical. Find out what the IRS says, what it can prove, what deadlines apply, and what resolution options are still open.
An irs tax debt attorney helps with exactly that. Not as a magician and not as a last-minute panic button. A good attorney acts as a navigator inside a formal system with rules, deadlines, strategic options, and workable outcomes. In many cases, the most valuable thing an attorney does first is bring order to a situation that feels chaotic.
That matters because you are not dealing with a rare event. In Fiscal Year 2024, the IRS Office of Chief Counsel handled over 51,000 new cases, and 60.4% came from the Small Business/Self-Employed Division, which covers many business owners, independent contractors, and self-employed taxpayers according to IRS Chief Counsel statistics. IRS disputes are common. They are serious, but they are not unusual.
That IRS Notice Arrived What Now
The first mistake people make is assuming the notice tells the whole story. It usually doesn't. A notice may reflect missing returns, substitute-for-return assessments, penalties that grew, or a payment history the taxpayer hasn't seen in one place before.
A common example is the business owner who knew they were behind, but didn't realize the IRS had already moved from billing into collection. Another is the self-employed taxpayer who thought they owed one year, only to learn the IRS has records issues across several years. The notice feels like the problem. It's often only the first visible piece of the problem.
What to do in the first few days
Start with the basics. Keep the envelope, the notice, and any prior letters together. Check the tax year involved, the response deadline, and whether the issue is about assessment, collection, missing returns, or a requested hearing.
Then avoid two bad reactions:
- Don't ignore it. Silence usually reduces your options.
- Don't send money blindly. If the amount is wrong, partial action without analysis can make the case messier.
- Don't call unprepared. If you speak with the IRS before understanding the file, you may miss important facts or deadlines.
Practical rule: Your first job is not to argue. Your first job is to identify exactly what the IRS says happened.
If you need help understanding the letter itself, a plain-English guide on responding to IRS letters can help you sort the notice before you decide on the next move.
Why calm action beats panic
Most tax debt cases are resolved through process, not drama. Deadlines matter. Records matter. Financial disclosures matter. So does knowing whether the IRS is still in the notice stage or already preparing stronger collection action.
That is where representation changes the tone of the case. Instead of reacting notice by notice, you build a plan. You identify what must be fixed first, what can wait, and which resolution tools fit your facts.
What an IRS Tax Debt Attorney Actually Does
People often say a tax debt attorney “negotiates with the IRS.” That's true, but it leaves out the essential work. The hard part isn't just asking for relief. The hard part is building a supportable case for the right kind of relief.
Representation starts with control of communication
The formal beginning is usually IRS Form 2848, the Power of Attorney. That document allows the attorney to step into communications, obtain records, and deal directly with the IRS within the scope of representation. For anxious clients, that alone changes the experience. You're no longer fielding every notice and call yourself.
After that, the attorney gathers transcripts, reviews filed and missing returns, checks assessment dates, and identifies whether the balance comes mostly from tax, penalties, interest, or some combination.
The debt has to be broken apart before it can be solved
Many cases turn on this specific point. A tax balance is not one simple number. In larger cases, penalties can comprise 20% to 50% of balances over $50K, according to this breakdown of tax debt analysis and collection options. That matters because the strategy changes depending on what is driving the debt.
An attorney typically reviews questions like these:
- Is the assessed tax correct? If the underlying number is wrong, collection strategy is not the first issue.
- Are penalties removable? Some cases support a request through Form 843.
- Is the client collectible right now? The IRS uses financial analysis, not sympathy, to answer that.
- Are unfiled returns blocking relief? Many resolution paths stay closed until filing compliance is fixed.
The same source notes that attorneys can seek penalty abatement through Form 843, with success around 35% for first-time requests, and can pursue Currently Not Collectible status, which can suspend enforcement actions for 12 to 24 months while the debt continues to accrue interest.
A good attorney doesn't start with “How do we settle this fast?” The better question is “What is actually in this balance, and what options does that balance allow?”
Why this is different from standard tax prep
A CPA or EA may be excellent at return preparation, bookkeeping, and planning. Tax debt resolution is different. The attorney is matching legal procedure, IRS collection rules, financial disclosure standards, and risk management.
That can include:
- reviewing whether the IRS followed required procedure
- preparing Form 433 financial disclosures in a way that reflects the client's real situation
- deciding whether to pursue installment terms, hardship status, or settlement
- handling the written and verbal advocacy that goes with that strategy
If you want a deeper look at the legal side of representation, this summary of the benefits of hiring a tax attorney explains where legal counsel adds value beyond basic tax compliance work.
When You Absolutely Need an Attorney
Some tax problems are manageable with limited help. Others call for legal representation early, before the case gets more expensive or harder to unwind.
Red-flag situations
You should strongly consider an attorney if your case involves any of the following:
- Large balances with multiple moving parts. Once the debt is substantial, the margin for error gets smaller and the paperwork gets more demanding.
- Payroll tax issues. These cases can expose owners, officers, and other responsible persons personally.
- Several years of unfiled returns. Until filing is corrected, many collection alternatives remain out of reach.
- A pending levy, garnishment, lien issue, or hearing deadline. Timing becomes part of the defense.
- A case that may end up in court or raises fraud concerns. This is legal territory, not just tax administration.
One area where this becomes especially clear is the Trust Fund Recovery Penalty. Many professionals refer those cases out because they can expose individuals personally for business payroll tax problems. According to industry commentary citing referral patterns and TFRP complexity, a 2023 AICPA survey found 68% of CPAs refer IRS dispute clients externally, and the IRS assessed $6.4 billion in TFRP in FY2023.
Why other professionals bring in tax debt counsel
The collaborative approach matters here. A tax debt case rarely exists in isolation.
A CPA may know the books but need controversy counsel to handle the IRS. A bankruptcy attorney may have a client whose tax debt won't disappear through the bankruptcy filing. A family law attorney may have a divorce stuck because one spouse's IRS debt affects property division, payment obligations, or the timing of settlement. A realtor or lender may need a tax lien issue addressed before a transaction can close.
The smartest tax debt work often happens in a team. The CPA fixes records. The bankruptcy lawyer handles the petition. The family lawyer protects the divorce posture. The tax debt attorney deals with the IRS.
When waiting makes things harder
Clients often call after trying to “see if it blows over.” Usually it doesn't. Delay can mean more notices, fewer appeal rights, tighter deadlines, and less room to shape the facts before the IRS forms its own view of the case.
If you're a professional advising a client, bringing in tax debt counsel early often helps your own case move forward. Instead of the tax issue sitting like a roadblock, it becomes a defined workstream with deadlines, documents, and a resolution track.
The Tax Resolution Process Explained
The process is less mysterious than it often seems. It's also more methodical. The strongest results usually come from disciplined case preparation, not broad promises.
Step one is analysis before commitment
A sensible engagement usually starts with a free tax debt analysis or similar initial review. That model is useful because not every case needs full representation, and not every taxpayer is a fit for every solution.
The early review should answer questions like:
- What years are involved?
- Are returns missing?
- Is the assessed debt likely accurate?
- Is there an immediate collection threat?
- Which resolution paths are realistically available?
That first stage is where a client learns whether the problem is primarily legal, financial, procedural, or some mix of all three.
Form 2848 changes who is steering the case
The legal process begins with IRS Form 2848, which allows the attorney to receive communications and negotiate directly with the IRS. As explained in this discussion of Power of Attorney and attorney-led tax settlement work, that authority is the basis for representation in collection and settlement matters.
That same source notes that attorney-led Offer in Compromise acceptance rates rose from 25% in 2019 to 44% in FY2023, often by proving doubt as to collectibility through detailed financial analysis. That doesn't mean every case should pursue an offer. It means the cases that qualify need careful factual development.
Many clients want the answer in the first call. The honest answer usually comes after records, transcripts, and financial documents are reviewed.
What the middle of the case looks like
Once representation begins, the work often follows this pattern:
- Records and transcripts are ordered and reviewed.
- Compliance issues are addressed, including missing returns if needed.
- Financial disclosures are prepared using the same type of information the IRS uses to judge ability to pay.
- Strategy is chosen based on the facts, not on what sounds most appealing.
- Negotiation and follow-up continue until the matter is resolved or redirected.
Common paths include installment agreements, hardship status, penalty work, or an offer where the facts support it. A practical guide to how to settle tax debt with IRS can help you understand how those options are evaluated.
What clients usually feel once the process starts
Relief often begins before the case is finished. Not because the debt vanishes, but because the confusion does. You know what the IRS says. You know what documents matter. You know the likely options and the weak points in the case.
That clarity is one of the biggest benefits of hiring an irs tax debt attorney. It turns a vague threat into a defined legal and financial project.
Attorney vs CPA vs EA Who Should You Call
The right professional depends on the problem. Many people assume these roles overlap completely. They don't.
Tax Professional Comparison Attorney vs CPA vs EA
| Attribute | IRS Tax Debt Attorney | CPA (Certified Public Accountant) | EA (Enrolled Agent) |
|---|---|---|---|
| Primary role | Legal advice and representation in tax disputes | Tax preparation, accounting, financial reporting, planning | Federal tax representation and return work |
| Best fit | Complex collection cases, litigation risk, payroll tax exposure, legal strategy | Books, returns, financial cleanup, planning, business records | Audits, appeals, return issues, many administrative IRS matters |
| Court representation | Yes, where authorized | Limited by role and jurisdiction | Limited by role and jurisdiction |
| Privilege considerations | Attorney-client privilege applies in legal advice contexts | Different confidentiality rules | Different confidentiality rules |
| Common value in tax debt case | Handles controversy, procedure, settlement framing, hearing and litigation posture | Reconstructs records and supports compliance work | Handles tax administration efficiently in many non-litigation matters |
| Ideal collaboration model | Leads legal strategy while working with CPA, EA, or other counsel | Supports the attorney with books, returns, and financial documentation | Supports representation with tax-specific administrative knowledge |
The practical way to decide
Call a CPA when the core problem is books, return preparation, entity accounting, or financial cleanup.
Call an EA when the issue is primarily administrative tax representation and the case does not carry significant legal complexity.
Call an irs tax debt attorney when the problem involves legal exposure, collection pressure, major procedural issues, litigation risk, or a need to coordinate with other counsel.
For many people, the best answer is not one professional instead of another. It's a coordinated team. A CPA may prepare delinquent returns. An EA may help organize tax records. The attorney handles legal strategy, procedural rights, and negotiation posture.
The wrong hire usually isn't a bad professional. It's a good professional being asked to solve the wrong kind of problem.
Choosing the Right Attorney and Understanding Fees
You get off the phone with one firm and still do not know what they would do, who would handle the work, or why the fee is what it is. That is usually a sign to keep looking.
A good tax debt attorney explains the plan in plain English before asking for a commitment. The first conversation should leave you with a clearer picture of the problem, the likely options, and what needs to happen first. In many cases, that also means coordinating with the professionals already involved in your life, including your CPA, a bankruptcy attorney, or family law counsel. Tax debt rarely sits in a vacuum.
What to ask before you sign
Ask direct questions and listen for direct answers.
- What types of tax debt matters make up most of your practice? Payroll tax issues, old unfiled returns, audits that turned into balances due, and collection cases all require different judgment.
- Will you review transcripts, notices, and filing history before recommending a strategy? A real recommendation starts with the file, not a sales script.
- Who will handle the work day to day? Many firms use staff appropriately, but you should know when the attorney steps in and what staff will do.
- How do you work with my other advisors? The right attorney should be comfortable coordinating with a CPA on return preparation or with other counsel if the tax issue affects a divorce, bankruptcy, business sale, or estate matter.
- How are fees charged, and what is included? Ask whether the fee covers investigation, compliance work, negotiations, appeals, and follow-up, or only the first phase.
One answer matters more than people expect. Ask what happens if the facts change after transcripts come in. Tax cases often look simpler at intake than they do after the record is reviewed.
Why free analysis first can make sense
Tax debt is common, and many firms market to people who are under pressure. That makes intake quality important.
A free analysis first model can be useful because it gives the attorney a chance to check the basics before quoting a strategy. That usually means reviewing IRS transcripts, looking at what returns are missing, identifying active collection deadlines, and spotting issues that may require another professional at the table. If a CPA needs to clean up books first, or if a bankruptcy lawyer needs to weigh in, that should come out early.
That kind of screening protects the client from paying for the wrong scope. It also protects the case.
Attorney Stephen A. Weisberg is one example of this approach. He offers a free tax debt analysis before representation through The W Tax Group. For many taxpayers, that early review is where they learn whether the likely path is an installment agreement, hardship status, penalty work, or a more targeted option such as an IRS Fresh Start Program overview.
Fees should match the work
Fees vary because the work varies. A case with current filings, clean records, and a straightforward payment proposal usually costs less than a case involving substitute for return assessments, revenue officer contact, payroll tax exposure, or multiple years of noncompliance.
What clients should want is not the lowest quote. They should want a clear scope.
Flat fees can work well when the problem is defined and the steps are predictable. Phased fees often make sense in larger matters because the first stage may involve investigation and compliance cleanup before anyone can responsibly price negotiation or appeals work. Hourly billing can be appropriate in cases with moving parts, especially when the attorney is coordinating with other advisors or handling legal issues outside ordinary IRS collections procedure.
If your tax problem also affects real estate decisions, cash flow, or broader settlement planning, related professionals may point you to practical resources on how to challenge property valuations. That kind of cross-disciplinary input can matter when the tax issue is only one part of the financial pressure.
A strong fee conversation is simple. You should know what the attorney is doing, what could change the price, and how the attorney will work with the rest of your professional team if the case requires it.
Common Outcomes and Your Next Steps
Many individuals approach this situation fearing there are only two possibilities. Pay everything now, or the IRS takes over. In reality, tax debt cases often end with one of several workable outcomes.
Common resolution paths
- Installment agreement. The debt is paid over time under terms the client can realistically maintain.
- Currently Not Collectible status. Collection pressure is paused when the taxpayer cannot presently pay.
- Penalty abatement. Parts of the balance may be reduced if the facts support relief.
- Offer in Compromise. In the right case, the IRS may accept less than the full balance.
- Procedural corrections. Some cases improve because notices, assessments, or collection steps were not handled properly.
A strong outcome is not always the most dramatic one. Sometimes the best result is a stable payment plan that prevents escalation. Sometimes it is hardship status that gives a business owner room to recover. Sometimes it is resolving the tax issue so a bankruptcy case, home sale, refinance, or divorce can finally move forward.
If you're looking at an IRS notice right now, your next step is simple. Get the file reviewed before you guess, before you call unprepared, and before you pay for a strategy that may not fit. If you want to understand one of the better-known relief frameworks, this overview of the IRS Fresh Start Program is a useful place to start.
If you want a clear assessment of your IRS options, schedule a free tax debt analysis with Attorney Stephen A Weisberg. You'll learn what the IRS is claiming, which resolution paths may fit your situation, and whether coordination with your CPA, bankruptcy attorney, family lawyer, or other advisor would help move the case forward.


