IRS Debt Lawyers: What They Do, When to Hire One
Learn what IRS debt lawyers do, when to hire one, how they differ from CPAs and EAs, typical outcomes, fee structures, and red flags to avoid.
In this article
- The Moment an IRS Notice Changes Everything
- The first hour is a triage exercise
- What IRS Debt Lawyers Actually Do
- They establish the facts
- They match the submission to the collection posture
- Tax Attorney vs CPA vs Enrolled Agent
- What the distinction means in practice
- Realistic Outcomes and Resolution Paths
- Installment agreements
- Offers in compromise
- Penalty relief
- Currently not collectible status
- How Fees Work and What to Expect
- What the engagement should cover
- Red Flags in the Tax Resolution Industry
- How to Choose the Right Attorney for Your Case
- Questions for the consultation
- Making a Smart Decision About Hiring
You open the mail after a long workday and find an IRS notice demanding payment. The number is large enough to disrupt payroll, a mortgage application, or your plans to keep the business open. You wonder whether to call the phone number on the notice, borrow money, ignore the letter, or hire one of the many firms advertising IRS debt relief.
The first question I ask isn't whether you qualify for an offer in compromise. It isn't even whether you can afford the balance. I ask where the case is in the IRS collection process. A qualified representative first confirms the notice, pulls the IRS transcripts, identifies the collection statute expiration date, and determines whether the agency is actively levying assets or merely billing you. The stage of the case usually matters more than the balance itself.
The Moment an IRS Notice Changes Everything
A small business owner opens a CP504 notice and sees an assessed balance of $42,000. The amount includes tax, penalties, and interest after a year of unanswered correspondence. Her first reaction is physical. Her stomach tightens, her hands become cold, and she starts calculating which account could cover the demand without missing payroll.
She has several instincts at once. She considers calling the number printed on the notice because the letter appears official. She considers borrowing against the business. She considers doing nothing because previous notices didn't immediately produce a levy. Then she searches for IRS debt lawyers and finds advertisements promising settlements, payment plans, and fast relief.
That is the point where panic creates expensive mistakes. A taxpayer may pay money that could have supported a defensible resolution, sign an agreement without understanding the collection consequences, or lose valuable time by assuming the IRS is inactive.
The first hour is a triage exercise
A competent attorney starts with the file, not a sales script. The initial review should answer practical questions:
- Is the notice genuine: The representative compares the notice number, tax periods, balance, and IRS contact information with the taxpayer's records.
- What does the IRS show: With a properly executed Form 2848 Power of Attorney, the representative can request transcripts and compare IRS data with filed returns, payments, assessments, and penalties.
- Is collection active: The file may show a levy threat, an existing bank levy, wage garnishment, federal tax lien activity, or ordinary billing.
- When does the collection period end: The collection statute expiration date can affect whether immediate payment, delay, or a negotiated arrangement makes sense.
- Are returns missing: The IRS often won't evaluate a resolution proposal responsibly while required returns remain unfiled.
Practical rule: Don't choose a resolution program until you know what the IRS has assessed, what it is doing now, and what deadline controls your next move.
The balance still matters, but it doesn't dictate the strategy by itself. A taxpayer with a modest liability facing an imminent levy may need crisis intervention, while a taxpayer with a larger balance and no active enforcement may have time for organized resolution planning. IRS debt representation begins with that distinction.
What IRS Debt Lawyers Actually Do
IRS debt lawyers don't tell clients to pay what they owe. Their work is a combination of record reconstruction, collection analysis, negotiation, document preparation, and deadline control. The useful deliverable is a defensible plan based on the IRS account, not a generic promise of relief.
They establish the facts
The attorney typically files Form 2848 so the IRS can communicate with the representative. The representative then reviews account transcripts, tax return transcripts, payment records, notices, prior agreements, and collection activity. Client memory is often incomplete, and IRS records can differ from the taxpayer's understanding, so both sides of the file require scrutiny.
That review may uncover an unapplied payment, a missing return, an incorrect assessment, an expired collection period, or a penalty that deserves separate analysis. It can also reveal that the IRS isn't actively pursuing the account, which may make an aggressive filing unnecessary.
They match the submission to the collection posture
The documents depend on the facts. A payment-plan request may involve Form 9465 or Form 433-D, supported by financial information and a realistic payment proposal. A hardship submission may use Form 433-F to support currently not collectible status. An offer in compromise generally requires Form 656 and a financial statement such as Form 433-A for an individual or Form 433-B for a business.
Other work products can include:
- Penalty abatement requests: The attorney develops a reasonable-cause or first-time-abatement position where the facts and IRS rules support it.
- Innocent spouse claims: The representative evaluates whether one spouse should be relieved from responsibility for an underpayment or understatement attributable to the other spouse.
- Appeals submissions: If the IRS rejects a proposed collection action or dispute, the attorney may present the case through the administrative appeals process.
- Audit defense: A debt case may require correcting the underlying assessment, because negotiating an inaccurate liability is poor lawyering.
Tax preparation and IRS representation aren't interchangeable. A preparer focuses primarily on filing accurate returns. A representative must also intercept collection activity, communicate with the IRS, protect deadlines, negotiate terms, and decide when the dispute belongs before Appeals or, where appropriate, the Tax Court.
The attorney also manages the human side of the case. That means telling the client which notices matter, what information is missing, when the IRS is expected to respond, and which events trigger additional work. Good representation reduces confusion without pretending that every account can be settled for less.
Tax Attorney vs CPA vs Enrolled Agent
All three professionals can be valuable in an IRS debt matter, but their credentials and legal authority differ. The right choice depends on whether the case is an administrative collection problem, a return or accounting problem, or a dispute that may require legal advice and court access.
| Credential | Licensing Body | Can Represent Before IRS | Tax Court Access | Attorney-Client Privilege | Best Fit For |
|---|---|---|---|---|---|
| Tax attorney | State bar | Yes, within authorized practice | Can litigate in Tax Court if admitted and otherwise qualified | Legal privilege may apply to legal communications under applicable law | Collection disputes, legal exposure, appeals, litigation, complex liability |
| CPA | State accountancy board | Yes, if eligible to practice before the IRS | No general Tax Court litigation authority | Confidentiality rules apply, but not the same full legal privilege as an attorney | Accounting reconstruction, return corrections, financial analysis, tax resolution |
| Enrolled Agent | IRS, through examination or qualifying experience | Yes, at administrative IRS levels, including Appeals | No Tax Court litigation authority | No attorney-client privilege | Administrative collection work, notices, payment arrangements, tax compliance |
What the distinction means in practice
A CPA may be the strongest choice when the central problem is inaccurate bookkeeping, unfiled business returns, or financial statements that need reconstruction before negotiations begin. An enrolled agent can be highly effective on administrative matters, particularly when the case doesn't involve litigation or broader legal exposure.
A tax attorney becomes more important when the IRS may assert personal liability, challenge the underlying legal position, refer conduct for criminal investigation, or require court-level advocacy. Attorneys can also provide legal advice beyond the mechanics of filing and collection. Privilege has limits and doesn't protect every business or accounting communication, so clients should ask the prospective representative how privilege applies to the specific engagement.
Don't hire based on title alone. Ask who will handle the file, whether that person has handled the same type of collection issue, and whether the firm regularly works with the IRS unit involved.
Realistic Outcomes and Resolution Paths
Before choosing a payment plan or compromise, determine whether the IRS is actively collecting and identify the account's stage. An ordinary notice, lien, levy, and garnishment create different risks and require different responses. The IRS has a substantial collection system, so a complete cancellation of the balance is not the usual outcome.
In fiscal year 2025, the agency reported collecting $117.5 billion in unpaid assessments from returns filed with additional tax due, with $73.1 billion remaining after credit transfers. The report also listed 13,112,485 taxpayer delinquent accounts in inventory, carrying $211.5 billion in assessed tax, penalties, and interest. The IRS collection activity data provides the scale needed to judge an individual case realistically.
Installment agreements
Payment plans remain the most common resolution path. FY2025 data showed 4,870,810 taxpayers in installment agreement inventory and $17.9 billion collected through installment agreements. The same IRS data helps explain why a structured payment arrangement is often more realistic than a full compromise.
An agreement can stop certain enforced collection actions while allowing the taxpayer to pay over time. The trade-off is direct: the taxpayer generally pays the liability, along with accruing interest and applicable penalties, and must stay current with future filing and payment obligations. A lawyer should test whether the proposed payment is affordable, rather than accept an amount that will fail after a few months.
Offers in compromise
An offer in compromise can settle the account for less than the full balance, but it is not a general discount program. A more recent FY2025 snapshot showed 38,797 offers received and 5,464 accepted. The Taxpayer Advocate Service's compromise analysis explains the screening involved in these cases.
The taxpayer must establish a recognized basis, such as doubt about collectibility or effective tax administration. The process requires detailed financial documentation, strict eligibility analysis, and a defensible proposal. Acceptance is never guaranteed, so an attorney should reject an offer strategy that the financial records cannot support.
Penalty relief
Penalty abatement can reduce the balance when reasonable cause or another valid basis exists. It does not remove the underlying tax and should not be marketed as an automatic percentage reduction. The attorney must connect the facts to the applicable IRS standard and support the request with records.
Currently not collectible status
Currently not collectible status may pause active collection when payment would create financial hardship. It is not forgiveness. Interest can continue to accrue, and the IRS may review the taxpayer's finances later. This option fits cases where the taxpayer has no realistic ability to pay, but the analysis must account for income, assets, expenses, and likely financial changes.
| Resolution Path | Best Fit Scenario | Typical IRS Outcome | Key Trade-off |
|---|---|---|---|
| Installment agreement | Stable income and capacity for scheduled payments | Structured repayment and reduced collection pressure | Balance, interest, and compliance obligations remain |
| Offer in compromise | Limited ability to pay and facts supporting compromise eligibility | IRS may accept a negotiated amount | Detailed financial proof and uncertain acceptance |
| Penalty abatement | Documented reasonable cause or qualifying history | Some penalties may be removed | Underlying tax generally remains |
| Currently not collectible | Payment would create genuine hardship | Active collection may pause | Interest may continue and the account can be reviewed |
Review tax debt relief options for an overview of the available approaches, then have the actual IRS account examined before selecting a resolution path.
How Fees Work and What to Expect
IRS debt lawyers generally charge through flat fees, hourly billing, or, less often, contingency arrangements. Each model can be fair when the scope is clear. None is fair when the firm uses vague promises to obtain a large payment before understanding the case.
Flat fees are common for defined administrative work. Straightforward installment-agreement matters may range from $1,500 to $4,000, while an offer in compromise may range from $7,000 to $15,000. Complex business audits or court matters may be billed hourly at $250 to $600 per hour. These figures are market ranges, not guarantees, and the facts can move a quote substantially.
What the engagement should cover
A written agreement should identify the work included and the events that create additional charges. Look for separate milestones such as:
- Intake and account review: Notice analysis, transcript review, return status, and collection-stage assessment.
- IRS contact: Filing the power of attorney and communicating with the assigned unit.
- Submission: Preparing the financial package, forms, legal position, and supporting records.
- Resolution: Negotiating acceptance, responding to IRS questions, or explaining the next available option.
Contingency pricing is uncommon because tax representation often requires substantial work before any result is known, and ethical rules restrict contingency fees in some settings. A retainer can be reasonable when it corresponds to defined work and appears in a written engagement letter. Suspicion is justified when a salesperson demands a large payment before reviewing notices or returns, refuses to explain what happens after intake, or claims that every case qualifies for the same program.
For another practical discussion of pricing, see the cost of a tax attorney. Ask whether calls, document review, appeals, amended returns, and litigation are included. A low quote can become expensive if nearly every necessary task is excluded.
Red Flags in the Tax Resolution Industry
The tax resolution business attracts firms that sell emotion before they analyze facts. A caller may be routed to a closer who has never reviewed an IRS transcript, hears the balance, and immediately recommends an offer in compromise. That isn't legal analysis. It's a sales process.
Be cautious when a firm:
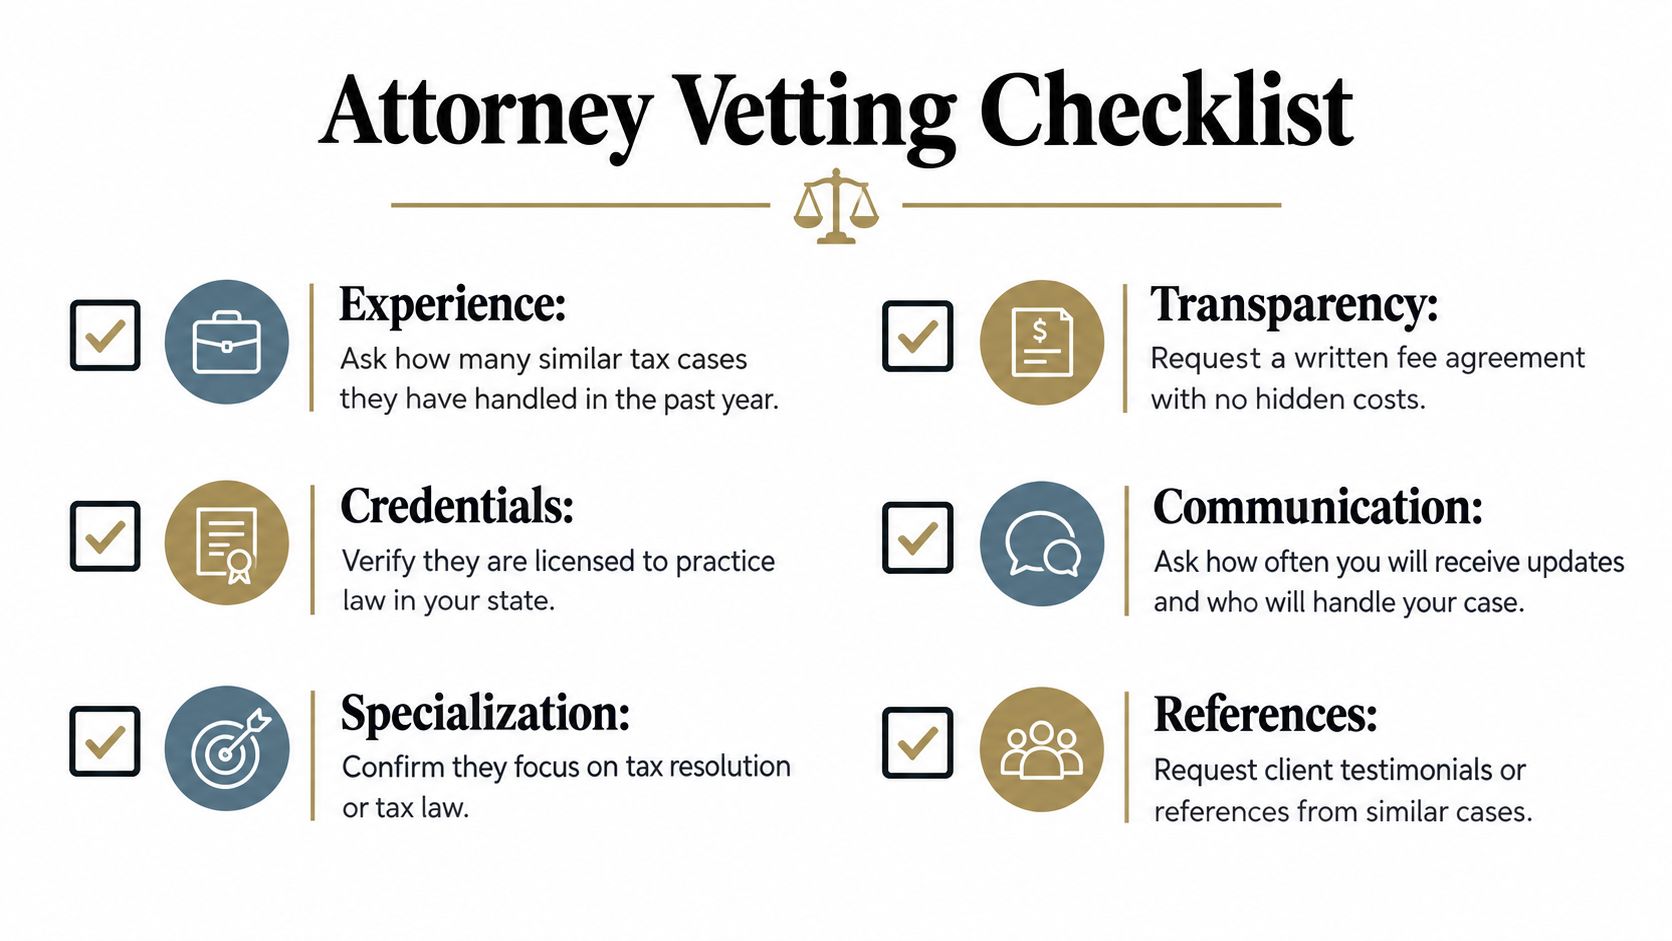
- Guarantees acceptance: No reputable representative can guarantee that the IRS will accept an offer in compromise.
- Promises pennies on the dollar: A settlement depends on eligibility, financial capacity, assets, income, expenses, and compliance. The slogan doesn't establish any of those facts.
- Quotes before reviewing records: A firm that hasn't seen the notice, returns, or transcripts can't responsibly know the scope of work.
- Demands a major upfront payment: A substantial retainer before meaningful case analysis deserves a precise explanation and written deliverables.
- Uses non-lawyers as the primary advisers: Intake staff can gather information, but a credentialed professional should conduct the first substantive evaluation.
- Treats every case alike: A taxpayer facing a levy needs a different response from someone receiving routine billing.
The honest answer may be that you should pay the tax, correct a return, request a payment plan, or defend the assessment rather than pursue a compromise. A candid attorney will explain those outcomes even when they produce a smaller engagement.
How to Choose the Right Attorney for Your Case
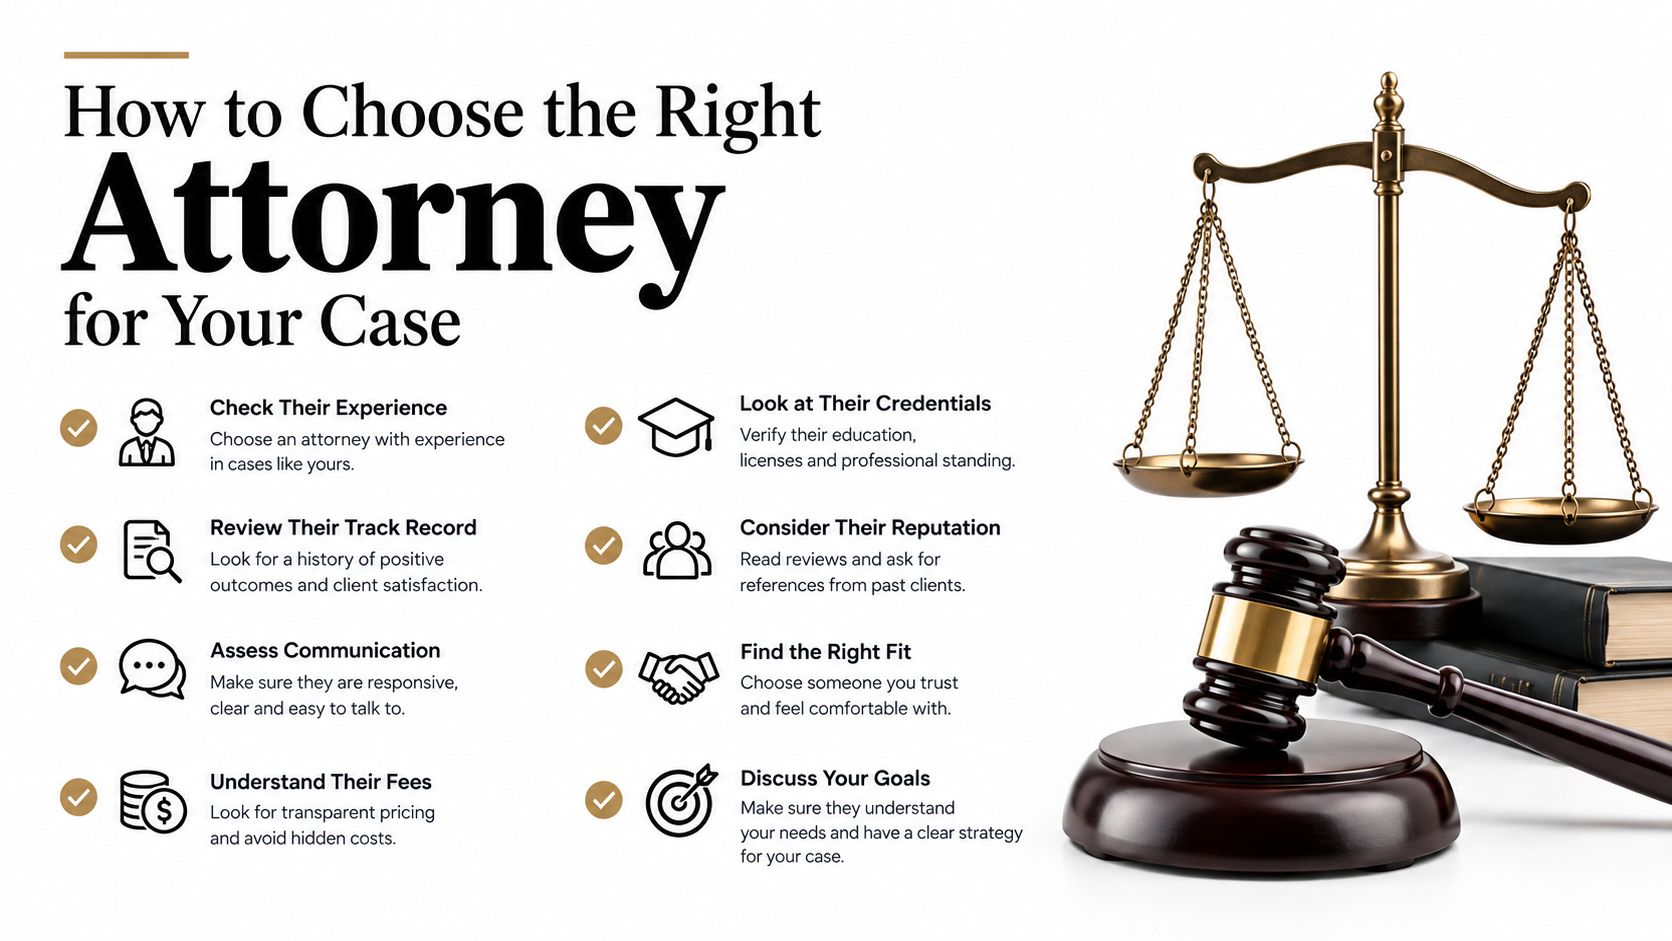
Start by testing the lawyer's questions. Before discussing a fee, the attorney should want the latest notice, tax periods, filed and unfiled returns, payment history, business structure, income, assets, and collection activity. If the conversation begins with a settlement promise instead of account triage, keep looking.
Questions for the consultation
Ask directly:
- Experience: How many similar cases have you handled in the past two years?
- Staffing: Who will work on my file, the partner, an associate, an enrolled agent, or administrative staff?
- Authority: Will you prepare and sign Form 2848, and will you represent me before Appeals or Tax Court if the case reaches that point?
- Strategy: What collection stage do you believe I'm in, and what facts could change your recommendation?
- Scope: Which returns, forms, IRS calls, appeals, and follow-up responses are included?
- Communication: Who sends updates, and how are additional calls or urgent notices billed?
Verify the attorney through the state bar's license lookup. Confirm current good standing and review disciplinary information where available. You should also confirm that the representative is authorized to practice before the IRS under the applicable Circular 230 rules. Membership in organizations such as the American College of Tax Counsel or a state tax section can signal serious focus, but membership isn't a substitute for checking experience and engagement terms.
A useful consultation also reflects understanding law firm client needs, especially clarity about communication, responsibility, and expectations. Compare two or three candidates when the notice stage allows it. A lawyer who won't provide an itemized written engagement letter shouldn't receive your retainer.
You can also review why use an IRS lawyer when deciding whether the matter requires legal representation rather than filing assistance alone.
Making a Smart Decision About Hiring
Hiring should turn on two questions: where the case sits in the IRS collection timeline and whether the representative handles that stage routinely. A pre-notice payroll problem calls for someone comfortable with employment-tax compliance and potential responsible-person exposure. A post-levy wage garnishment requires rapid collection intervention. A taxpayer at ordinary notice stage may have time to compare candidates, while someone facing a levy or lien should prioritize a firm with documented same-week representation capability.
That stage-based approach is more useful than choosing a firm because its advertisement promises the largest reduction. When to hire a tax attorney can help you evaluate the point at which professional involvement becomes worthwhile.
Pull your most recent IRS notice now. Identify the notice number, tax period, deadline, and IRS unit listed, then schedule consultations with two attorneys who regularly handle that exact collection stage before paying anyone.
Tax Attorney Stephen A Weisberg provides IRS representation, transcript and notice review, and tax debt resolution services for individuals, business owners, and professionals dealing with collection problems. Visit Tax Attorney Stephen A Weisberg to request a Tax Debt Analysis and discuss whether representation is appropriate for your specific IRS case.


