How Do I Calculate Alternative Minimum Tax for 2026
Struggling with how do I calculate alternative minimum tax? This guide breaks down Form 6251, AMT adjustments, and exemptions with real-world examples.
In this article
- What Is the Alternative Minimum Tax Anyway?
- Who Is Still at Risk for the AMT?
- Potential 2026 AMT Triggers at a Glance
- Why You Need to Pay Attention Now
- Finding Your Alternative Minimum Taxable Income
- The Big Three Adjustments That Trip People Up
- Pulling It All Together on Form 6251
- From AMTI to Tentative Tax: Applying the Exemption and Rates
- The AMT Exemption and its Sneaky Phase-Out
- Applying the AMT Tax Rates
- Calculating Your Tentative Minimum Tax
- The Final Showdown: Comparing Regular Tax vs. AMT
- A Start-to-Finish Example
- AMT vs Regular Tax a Worked Example
- The Silver Lining: The AMT Credit
- Proactive Strategies to Minimize Your AMT Risk
- Master Your Timing
- Make Strategic Investment and Deduction Choices
- Look Ahead to the Post-TCJA Cliff
- Common Questions We Hear About the AMT
- What Happens If I Pay AMT by Mistake?
- How Does Business Depreciation Affect AMT?
- Can I Use the AMT Credit to Get a Refund?
- What Is the Difference Between the Individual and Corporate AMT?
Calculating your potential Alternative Minimum Tax (AMT) bill feels a lot like doing your taxes twice. You start with your regular taxable income, then you systematically add back certain deductions that the AMT rules don't allow. After subtracting a special AMT exemption, you apply the AMT tax rates to get what's called your "tentative minimum tax."
If that tentative tax number is higher than your regular income tax, you owe the difference. That difference is the Alternative Minimum Tax.
What Is the Alternative Minimum Tax Anyway?
Ever get the feeling there's a shadow tax system lurking behind the one you know? That’s pretty much what the AMT is. It’s not a penalty; it's a completely parallel tax system with its own set of rules for what counts as income and what you can deduct.
The entire point of the AMT is to make sure high-income individuals and businesses who are great at using deductions and other tax breaks still pay a fair share.
This parallel system actually dates back to 1969. Congress was reacting to a report that 155 ultra-wealthy households had legally used so many tax strategies that they paid zero federal income tax. The AMT was created to prevent that from happening again. For decades, though, its parameters weren't adjusted for inflation, so it started to hit more and more people.
By 2017, the AMT was a serious headache for the upper-middle class, affecting an estimated 5 million taxpayers. But then the Tax Cuts and Jobs Act (TCJA) of 2017 came along and dramatically raised the AMT exemption amounts. The change was so significant that the number of taxpayers paying AMT plummeted to just 200,000 by 2018—a massive 96% drop.
Who Is Still at Risk for the AMT?
Even after the TCJA, the AMT is far from dead. It just has a more specific list of targets now, often including self-employed professionals, small business owners, and employees with certain types of compensation.
You might find yourself in the AMT crosshairs if you have:
- High State and Local Tax (SALT) Deductions: The TCJA capped this deduction at $10,000 for regular tax purposes. But for the AMT, the entire deduction is disallowed. If you live in a high-tax state like California or New York, this is probably the single biggest AMT trigger.
- Exercised Incentive Stock Options (ISOs): This is a classic trap that catches many tech employees and executives by surprise. When you exercise ISOs, the paper profit—the difference between the stock's fair market value and what you paid—is considered income for AMT purposes that year, even if you haven't sold a single share.
- Interest from Private Activity Bonds: Most municipal bond interest is tax-free. But interest from private activity bonds (a specific type of muni bond that benefits a non-governmental project) is tax-free for regular tax but fully taxable under the AMT.
- Large Capital Gains: While the tax rates for long-term capital gains are the same for both systems, a huge gain can push your total income so high that you start to lose your AMT exemption. This phase-out can indirectly trigger an AMT liability.
To help you quickly identify if you're at risk, here are some of the most common financial events that could push you into AMT territory. Pay close attention if any of these apply to your situation, as they often require a closer look at your tax planning.
Potential 2026 AMT Triggers at a Glance
| Triggering Event or Deduction | Who Is Commonly Affected | Why It Triggers AMT |
|---|---|---|
| High state and local tax payments | Residents of high-tax states (e.g., CA, NY, NJ) | The entire SALT deduction (capped at $10,000 for regular tax) is added back to income for AMT. |
| Exercising Incentive Stock Options (ISOs) | Tech employees, startup founders, executives | The "bargain element" (paper profit) is counted as AMT income in the year of exercise, not sale. |
| Significant miscellaneous deductions | Employees with specific work-related expenses | Certain deductions, like impairment-related work costs, are disallowed under AMT rules. |
| Interest from private activity bonds | Investors seeking tax-free income | This specific type of municipal bond interest is tax-exempt for regular tax but taxable for AMT. |
| Large long-term capital gains | Investors, business owners selling assets | A large gain can push your income past the AMT exemption phase-out, increasing your tentative minimum tax. |
| Depreciation on business property | Small business owners, real estate investors | AMT requires a slower depreciation method (150% declining balance) than the regular tax system often allows. |
If you've checked off one or more of these boxes, it doesn't automatically mean you'll owe AMT, but it's a strong signal that you need to run the numbers. Proactive planning can make all the difference.
Key Takeaway: The AMT isn't a penalty for success; it's a structural backstop in the tax code. The first step is figuring out if your income sources or deductions fall into these common trigger categories.
Why You Need to Pay Attention Now
Here’s the critical part: The generous AMT exemptions from the TCJA are temporary. They are set to expire at the end of 2025.
Unless Congress steps in to extend them, the exemption amounts will drop back to their much lower, pre-TCJA levels for the 2026 tax year. To get a better handle on the basics of this parallel system, it helps to review What Is Alternative Minimum Tax and its mechanics.
With this change on the horizon, a whole new wave of business owners and high-earning professionals could get hit with an unexpected AMT bill. Now is the time to start planning. And while you're at it, understanding the fundamentals of tax allowances and their definitions can provide more context for your overall tax strategy.
Finding Your Alternative Minimum Taxable Income
So, where do we begin? The first move in figuring out if you owe Alternative Minimum Tax is to calculate your Alternative Minimum Taxable Income (AMTI). The best way to think about this is that you're essentially rebuilding your income from scratch, but using the AMT's rulebook instead of the regular tax code's.
You'll start with a number you already know: the taxable income from your Form 1040. From there, you'll start adding back certain deductions and including specific kinds of income that the regular tax system lets you ignore. These are what the IRS calls adjustments and preference items.
This process can feel a bit strange, but its history shows why it exists.
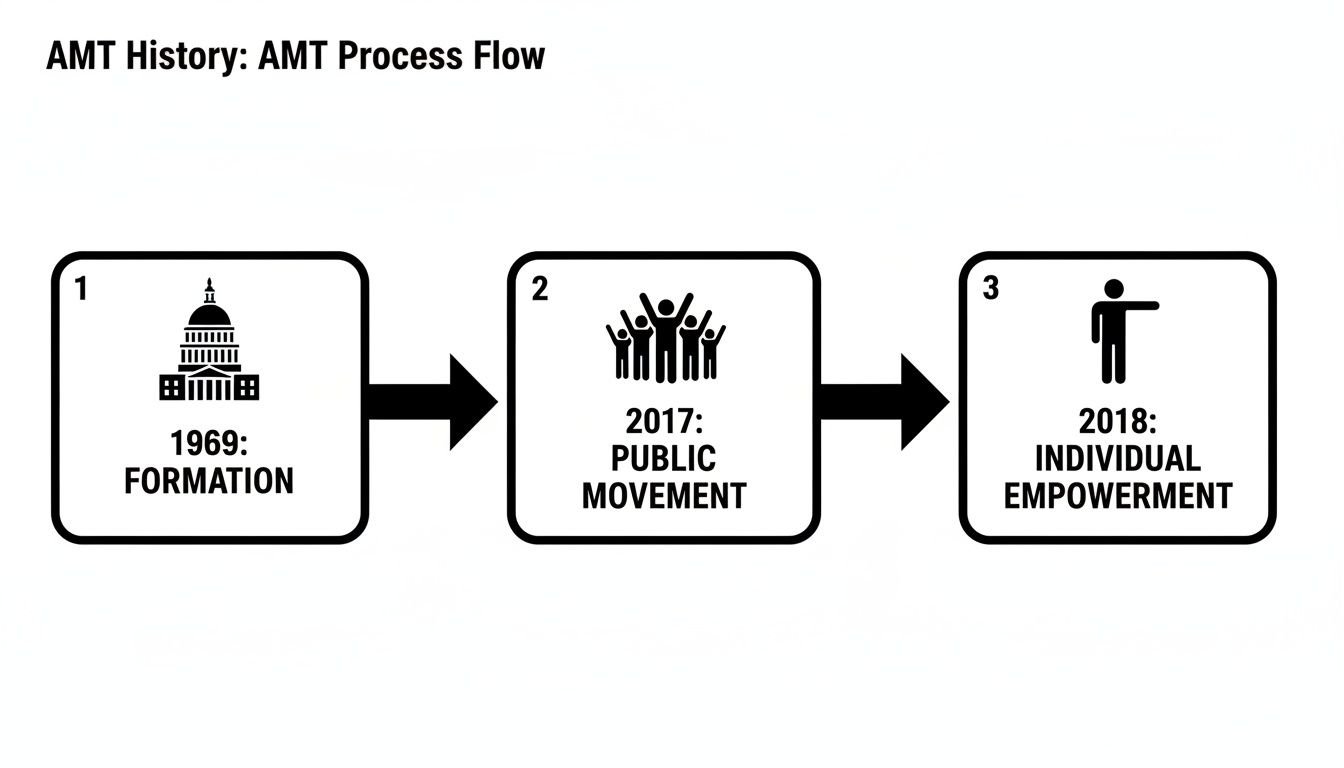
As you can see, the AMT's scope grew for decades. The Tax Cuts and Jobs Act of 2017 (TCJA) changed the game, dramatically cutting the number of people who had to pay it and refocusing the tax on a smaller group of high-income earners.
The Big Three Adjustments That Trip People Up
While the IRS lists dozens of potential AMT adjustments, my experience shows that just a few are responsible for pushing most entrepreneurs, investors, and high-earners into AMT territory. Let’s look at the most common culprits.
1. State and Local Taxes (SALT)
This is, without a doubt, the most frequent trigger, especially if you live in a high-tax state. For your regular taxes, you get to deduct the state and local taxes you've paid, though it's capped at $10,000 per household.
When it comes to the AMT, that deduction vanishes completely. You have to add back every single dollar you claimed under the SALT deduction. For a small business owner in California or New York, this one adjustment alone can instantly bump their AMTI up by $10,000.
2. Incentive Stock Options (ISOs)
Here's a classic trap for anyone working in the tech world or for a company that offers stock options. When you exercise ISOs, the paper profit—the difference between the stock's fair market value and what you paid for it (the "bargain element")—isn't counted as regular income until you actually sell the shares.
But the AMT plays by a different set of rules. That entire bargain element is treated as income in the year you exercise the options, not when you sell.
Let's put this into perspective: Imagine you work for a startup and exercise 1,000 incentive stock options.
- Your exercise price (what you pay) is $5 per share.
- The stock’s fair market value on the day you exercise is $55 per share.
Your bargain element is calculated like this: ($55 - $5) x 1,000 shares = $50,000.
Even if you don’t sell a single share, you have to add that $50,000 paper gain to your income when figuring out your AMTI. This is how people get hit with a massive, and often completely unexpected, tax bill.
3. Tax-Exempt Interest from Private Activity Bonds
Most of the time, interest earned from municipal bonds is tax-free for both regular tax and AMT purposes. But there's a huge exception: interest from private activity bonds. These are special bonds a city or state might issue to fund a project that benefits a private, non-governmental group, like a new sports stadium or airport terminal.
While that interest income is tax-free on your Form 1040, you must add it back when calculating your AMTI. An investor who carefully built a portfolio of what they thought was tax-free income can get a nasty surprise when they discover it's fully taxable under the AMT.
Pulling It All Together on Form 6251
All of this comes together on IRS Form 6251, the official worksheet for the AMT. The first part of this form is where you'll make all these adjustments.
You'll take your regular taxable income and start adding things back: the full amount of your SALT deduction, the bargain element from any ISOs you exercised, and other preference items. You'll also see lines for things like depreciation and net operating losses, which are calculated differently for AMT.
Key Insight: Remember, the goal here isn't to find your final tax bill just yet. It's to arrive at a new, adjusted income figure—your AMTI. This number is the bedrock for the entire calculation.
Once you’ve gone through Form 6251 and added back all the required items, you'll have your AMTI. This is the crucial number you'll carry forward to the next part of the process: applying the AMT exemption.
From AMTI to Tentative Tax: Applying the Exemption and Rates
You've done the heavy lifting and calculated your Alternative Minimum Taxable Income (AMTI). That number is the foundation for everything that comes next. Now, we move on to the AMT exemption, which is basically a sizable deduction meant to keep most middle-income taxpayers from ever having to worry about this parallel tax system.
But there’s a catch, and it’s a big one for higher earners. This exemption isn't a given; it starts to disappear once your AMTI crosses a certain line. This "phase-out" is often what pulls unsuspecting taxpayers into the AMT's reach.
The AMT Exemption and its Sneaky Phase-Out
For the 2026 tax year, the AMT exemption offers a substantial starting deduction, with the exact amount depending on your filing status. These figures are indexed for inflation, but they serve as our baseline.
The real story here is the phase-out. As your income goes up, this benefit goes down. The rule is simple but harsh: for every dollar your AMTI is above the phase-out threshold, you lose 25 cents of your exemption.
Let's see how this works with a practical example.
Example: The Vanishing Exemption
Imagine you're a single filer with a 2026 AMTI of $750,000.
- The single filer exemption for 2026 is $93,600.
- The phase-out threshold for single filers kicks in at $666,700.
Here’s how we'd figure out your actual exemption:
First, find out how far over the threshold you are: $750,000 (Your AMTI) - $666,700 (Threshold) = $83,300
Next, calculate how much your exemption is reduced: $83,300 (Excess Income) x 0.25 = $20,825 (Exemption Reduction)
Finally, subtract the reduction from the full exemption amount: $93,600 (Full Exemption) - $20,825 (Reduction) = $72,775 (Your Allowable Exemption)
Just like that, your exemption is cut by more than $20,000. If your income were high enough, that $72,775 could shrink all the way down to zero.
Applying the AMT Tax Rates
Once you've nailed down your allowable exemption, you subtract it from your AMTI. The number you're left with is the income that will actually be taxed under the AMT rules.
AMT Income Base = AMTI - Allowable AMT Exemption
The good news? The AMT tax system is much simpler than the regular one. Instead of seven tax brackets, there are just two: 26% and 28%.
For the 2026 tax year, this is how it breaks down:
- You'll pay a 26% rate on the first $232,600 of your AMT income base.
- You'll pay a 28% rate on every dollar above $232,600.
Picking up with our example, your AMT income base would be $750,000 (AMTI) - $72,775 (Allowable Exemption) = $677,225.
Calculating Your Tentative Minimum Tax
Now we have all the pieces to calculate the Tentative Minimum Tax (TMT). This is the final number from the AMT side of the equation before we compare it to your regular tax bill.
Let's finish our example with the $677,225 income base:
Tax the first portion at 26%: $232,600 x 0.26 = $60,476
Figure out how much falls into the 28% bracket: $677,225 (Income Base) - $232,600 = $444,625
Tax that remaining portion at 28%: $444,625 x 0.28 = $124,495
Add the two amounts to find your TMT: $60,476 + $124,495 = $184,971
Your Tentative Minimum Tax is $184,971. This is what your tax bill would be if the AMT rules were the only ones that applied. The final step is to put this number next to your regular tax liability and see which one is higher—because you have to pay the higher of the two.
The Final Showdown: Comparing Regular Tax vs. AMT
After all the calculations—your Alternative Minimum Taxable Income (AMTI), the exemption, and the tax rates—you’ve arrived at your Tentative Minimum Tax (TMT). This is the home stretch. Now you just need to compare that TMT figure to the regular income tax you calculated for your Form 1040.
The rule here is simple: you only pay the Alternative Minimum Tax if your TMT is higher than your regular tax. It’s a common misconception that you pay the entire TMT. Instead, the AMT you owe is just the difference between the two numbers.
Think of it as a "top-up" tax. The IRS is basically saying your tax bill has to reach a certain floor, and if your regular tax doesn't get you there, the AMT makes up the difference.
A Start-to-Finish Example
Let's put all the pieces together with a real-world scenario. We'll follow a hypothetical small business owner to see how this plays out.
Imagine a single filer whose AMTI lands at $300,000. We already know they got to this number by adding back items disallowed under AMT rules, like their $10,000 state and local tax (SALT) deduction and a $20,000 bargain element from exercising incentive stock options (ISOs).
With an AMTI of $300,000, our business owner is well under the exemption phase-out threshold, so they can take the full AMT exemption for the year. We subtract that exemption, apply the two-tiered AMT rates of 26% and 28%, and arrive at the Tentative Minimum Tax.
Let’s say their TMT comes out to $55,094. If their regular tax bill was only $40,000, they’re facing an AMT bill of $15,094. Those add-backs really matter—I've seen many cases where AMT inflates a final tax liability by 10-20%, a figure backed by IRS data on tax debt. Some insights from tax pros at Bench.co highlight how this happens.
To really see the divergence, a side-by-side comparison is the best way to visualize it.
AMT vs Regular Tax a Worked Example
This table walks through how our business owner’s tax liability is determined under both systems, showing exactly where the numbers differ and why one tax bill ends up higher than the other.
| Calculation Step | Regular Tax Calculation | Alternative Minimum Tax (AMT) Calculation |
|---|---|---|
| Starting Income | Taxable Income (e.g., $270,000) | AMTI (e.g., $300,000) |
| Deductions/Exemptions | Standard/Itemized Deductions Applied | AMT Exemption Applied |
| Tax Rates Applied | 7 Brackets (10% to 37%) | 2 Brackets (26% and 28%) |
| Calculated Tax | Regular Tax Liability: $40,000 | Tentative Minimum Tax (TMT): $55,094 |
| Final Comparison | $40,000 is less than $55,094 | $55,094 is greater than $40,000 |
The Verdict: Because the TMT ($55,094) is higher than the regular tax liability ($40,000), the taxpayer must pay the difference. The AMT owed is $15,094 ($55,094 - $40,000).
This final amount, $15,094, is what gets entered on the appropriate line of your Form 1040. Your total tax for the year becomes your regular tax of $40,000 plus that $15,094 AMT, totaling $55,094. You can see how this fits into the bigger picture in our guide on how to calculate your tax liability step-by-step.
The Silver Lining: The AMT Credit
Getting hit with an AMT bill is never fun, but don't overlook the potential silver lining: the Minimum Tax Credit.
The tax code recognizes that some items triggering AMT are about timing, not permanent tax avoidance. Take those ISOs from our example. You pay AMT on the "paper profit" now, but you'll also pay regular capital gains tax when you eventually sell the stock.
To prevent double taxation, the tax system allows you to claim a credit for the AMT paid on these types of "deferral" items. This credit is tracked on Form 8801, Credit for Prior Year Minimum Tax. You can carry it forward indefinitely to reduce your regular tax in future years (though not below that year's TMT). It’s a valuable asset, so make sure you don't forget about it.
Proactive Strategies to Minimize Your AMT Risk
Knowing how to run the numbers on Form 6251 is one thing, but truly outsmarting the Alternative Minimum Tax requires a shift in mindset. You need to move from defense to offense. This means looking down the road and making strategic financial moves all year long, not just scrambling when tax season hits.
In my experience, the biggest AMT surprises don't come from complex tax schemes. They come from a single, poorly timed financial event. Exercising a huge chunk of incentive stock options (ISOs) or simply underestimating the bite of living in a high-tax state are classic tripwires. Smart planning is all about controlling the variables you can.
Master Your Timing
When it comes to managing the AMT, timing is everything. Since the tax is figured on a year-by-year basis, simply moving income and deductions across the December 31st finish line can make a world of difference.
- Time Your Incentive Stock Option (ISO) Exercises: The "bargain element" of an ISO is a notorious AMT trigger. Instead of cashing in a massive block of options in one year, consider a staggered approach. Spreading the exercises over a few years can keep your annual AMTI safely below the exemption threshold.
- Manage Capital Gains: Got a big capital gain on the horizon from selling an asset? Think carefully about its AMT impact. A large gain can rocket your income high enough to slash or even wipe out your AMT exemption, triggering the tax. You might consider harvesting some losses to offset those gains or, if possible, splitting the sale across two tax years.
- Accelerate or Defer Income: If you're a business owner, you have a bit of an edge here. If you see you’re getting close to the AMT danger zone, you could try to accelerate some income into the current year to make full use of your deductions. Or, you might defer that income into next year to keep yourself under the limit.
Make Strategic Investment and Deduction Choices
The investments you choose and the deductions you claim have a direct line to your potential AMT bill. Paying close attention here can really pay off.
For instance, a simple but effective strategy is to maximize every business write-off you're entitled to. If you use your car for work, make sure you meticulously track business mileage for maximum tax deductions. Lowering your regular taxable income can often be enough to keep you out of AMT territory.
Your investment portfolio is another key area. Tax-exempt municipal bonds are a popular way to generate tax-free income, but there's a catch. Be wary of private activity bonds. While the interest from these is tax-free for your regular return, it's fully taxable under the AMT.
A Proactive Tip: Before you sink money into a municipal bond fund, take a minute to look under the hood. If you see that a big chunk of the fund's income is from private activity bonds, it could create a nasty AMT headache you weren't expecting.
Look Ahead to the Post-TCJA Cliff
This is critical: The generous AMT exemptions created by the Tax Cuts and Jobs Act (TCJA) are scheduled to expire at the end of 2025. If Congress doesn't intervene, the exemption amounts will snap back to their much lower, pre-TCJA levels for the 2026 tax year.
This "tax cliff" is a big deal. It means a whole new wave of small business owners and high-income professionals who have never worried about the AMT will suddenly be at risk. The planning strategies you put in place now are about to become even more essential. Getting a handle on how to reduce your overall tax liability is the foundation for this kind of long-term preparation.
Thinking ahead isn't just a good idea anymore; it's a necessity. This is where getting professional guidance can turn a potential tax nightmare into a manageable part of your financial life, ensuring you’re ready for whatever comes next.
Common Questions We Hear About the AMT
Even after walking through Form 6251 line by line, it's natural to have some lingering questions. The Alternative Minimum Tax is notoriously tricky, and I've seen how specific situations can create a lot of confusion. Let's tackle some of the most common issues that come up.
What Happens If I Pay AMT by Mistake?
It’s a frustrating feeling to realize you’ve overpaid the IRS, but don't worry—it's fixable. If you discover you paid AMT when you didn't actually owe it, the solution is to file an amended tax return.
You'll need to use Form 1040-X, Amended U.S. Individual Income Tax Return. On this form, you'll recalculate your tax liability without the AMT and clearly explain the error. Once the IRS processes the amended return, you'll receive a refund for the overpayment. Just make sure you keep excellent records of both your original and corrected calculations.
How Does Business Depreciation Affect AMT?
This is a big one, and it often catches even seasoned business owners by surprise. The core of the issue is that the rules for deducting depreciation are different for regular tax versus AMT.
For your regular tax return, you’re likely using an accelerated method (like the 200% declining balance) to get bigger deductions upfront. The AMT, however, forces you to use a slower, less generous method—usually the 150% declining balance method. This creates a gap where your AMT depreciation deduction is smaller. That difference gets added back to your income when calculating your Alternative Minimum Taxable Income (AMTI), which can easily push you into AMT territory.
Can I Use the AMT Credit to Get a Refund?
The Minimum Tax Credit you earn from paying AMT is a great tool, but it's important to understand its limitations. The credit is nonrefundable.
What does that mean in practice? It can wipe out your regular tax bill for the year, but it can't go below zero to generate a refund.
Think of it this way: if your regular tax liability is $5,000 and you have a $7,000 AMT credit carryforward, you can use $5,000 of that credit to bring your tax bill to $0. The remaining $2,000 of the credit isn't lost—it simply rolls over to the next year, ready to be used against a future tax liability.
What Is the Difference Between the Individual and Corporate AMT?
It’s easy to get these two mixed up since they share a name, but the individual AMT and the Corporate Alternative Minimum Tax (CAMT) are completely different animals.
- Individual AMT: This is what we've been focused on. It applies to individuals, estates, and trusts and is calculated on Form 6251. It’s triggered by personal items like exercising ISOs or high state and local tax deductions.
- Corporate AMT (CAMT): This is a separate tax that only applies to massive corporations with average profits exceeding $1 billion. It was created by the Inflation Reduction Act of 2022 and is calculated based on a company's financial statement income ("book income"), not its regular taxable income.
If you're a small business owner, sole proprietor, or operate through an S Corp or LLC, you only need to concern yourself with the individual AMT on your personal return. The CAMT won't affect you. Managing these details is why having a solid estimated tax payment schedule is so crucial for business owners.
Tackling the AMT requires a proactive strategy and a firm grasp of the tax code's finer points. At Attorney Stephen A Weisberg, we specialize in guiding individuals and business owners through complex tax challenges just like this. If you're worried about the AMT or facing other IRS issues, start with our FREE Tax Debt Analysis to see exactly how we can help. Contact us today to find some clarity and get control of your tax situation.


